The QuantMonitor Live Portfolio continues to focus on controlled, systematic growth rather than aggressive equity acceleration. The primary objective remains long-term robustness: strict risk management, diversification across instruments, and avoiding strategies that rely on excessive leverage or fragile market conditions.
This update summarizes the first nine months of live trading, highlights portfolio-level performance, breaks down results by instruments, and addresses an important seasonal risk as we approach the year-end period.
Nine Months of Live Trading
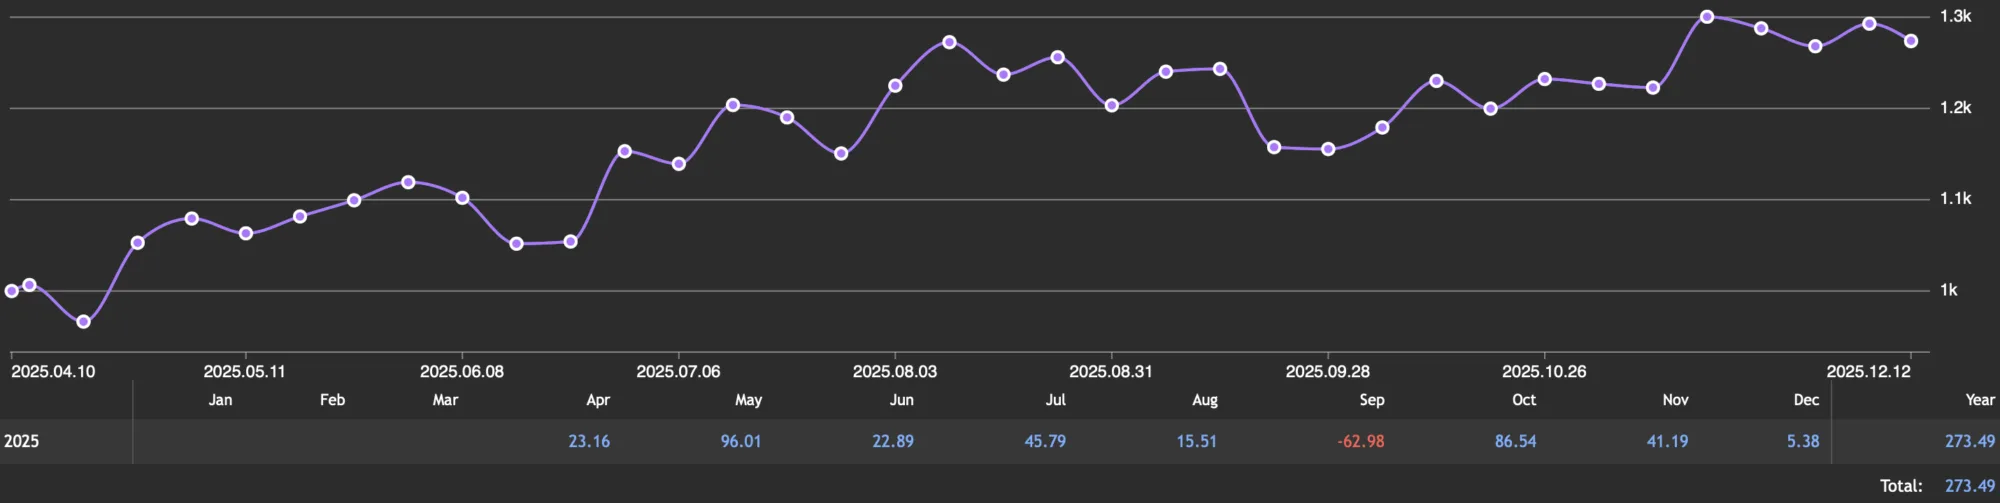
The portfolio has now completed nine consecutive months, with eight of them closed in profit. This consistency is intentional.
Rather than chasing steep equity curves, the portfolio is designed to:
- Limit drawdowns
- Keep exposure diversified across markets
- Maintain stability during different volatility regimes
Short-term stagnation or smaller monthly gains are accepted trade-offs for long-term capital preservation.
Overall Portfolio Performance
- Initial capital: $1,000
- Current balance: ~$1,273
- Net profit: ~$273
- Total return: ~27%
- Maximum drawdown: low and controlled
The equity curve shows steady progression, interrupted only by shallow, quickly recovered drawdowns. There are no sharp spikes or collapses — exactly the behavior expected from a risk-controlled portfolio.
Performance by Instruments
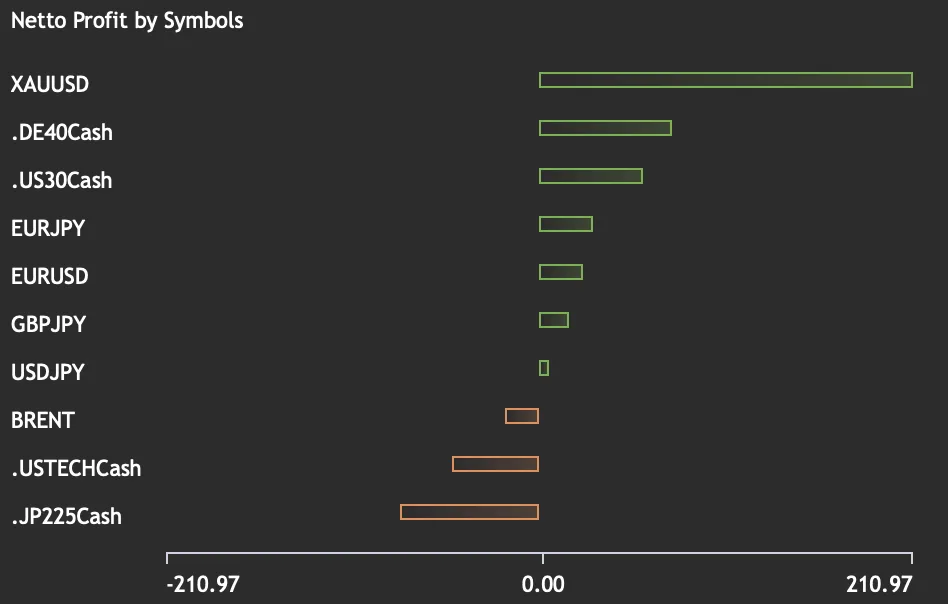
The portfolio trades a mix of indices, currencies, and commodities, each playing a specific role.
Top contributors:
- XAUUSD (Gold) – strongest positive contributor, benefiting from well-behaved volatility
- DE40 (DAX) – solid, consistent gains
- US30 – moderate but stable contribution
- EURJPY / EURUSD – smaller, steady profits
Weaker or negative contributors:
- USTECH / JP225 – periods of choppy price action
- BRENT – limited exposure, slightly negative overall
This distribution confirms that no single instrument dominates portfolio risk, which is a key design principle.
Swap Costs and Carry Management
One important operational aspect is swap cost management.
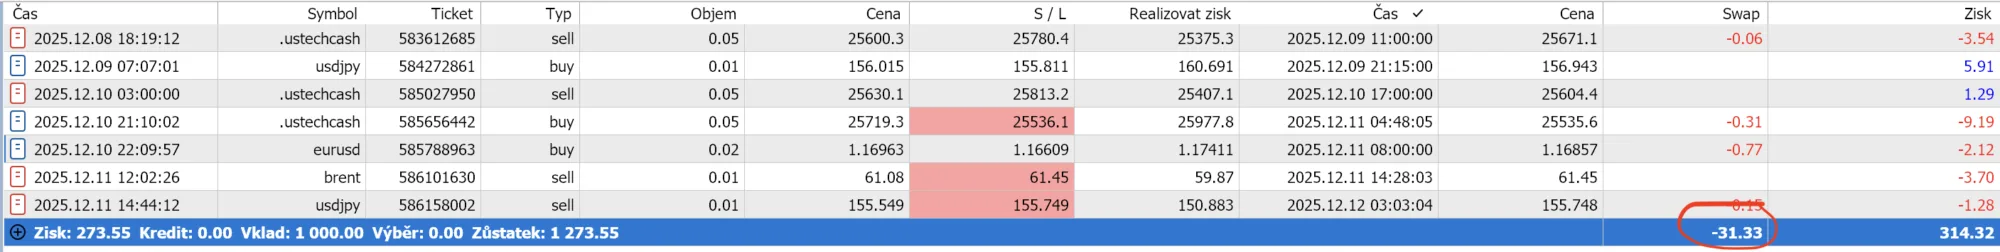
As shown in the swap overview:
- Total swap cost ≈ 10% of total net profit
- Swaps are monitored continuously
- Strategies are adjusted to avoid unnecessary overnight exposure where possible
Swap costs are therefore meaningful but controlled, and they remain an acceptable trade-off for diversification and strategy stability.
Risk Control Philosophy
The portfolio is deliberately not optimized for maximum growth.
Core principles:
- Conservative position sizing
- No martingale or grid escalation
- Controlled exposure during high-risk market regimes
- Preference for robustness over curve-fitting
This approach may look less exciting in strong bull phases, but it significantly improves survival during adverse market conditions.
Important Notice: Year-End Market Risk
As we approach Christmas and New Year, traders should be aware of the following:
- Markets are closed for several days
- Liquidity drops sharply
- Weekend and holiday gaps become more likely
- Stops may be skipped during reopenings
⚠️ Recommendation:
Consider disabling your strategies or significantly reducing exposure during the holiday period. Capital preservation is more important than chasing returns when market conditions are structurally distorted.
Final Thoughts
The QuantMonitor Live Portfolio continues to validate its core thesis:
consistent, risk-controlled trading can outperform aggressive approaches over time.
The focus remains unchanged:
- Protect capital
- Avoid deep drawdowns
- Grow steadily across market cycles
Thank you for following the live results — the next update will reflect how the portfolio navigates the year-end transition and the start of the new trading year.