QUANTMONITOR LIVE PORTFOLIO — Monthly Performance Update
Welcome to the monthly update of the QuantMonitor Live Portfolio. This is a real-money portfolio where we publish results transparently and, just as importantly, we

Welcome to the monthly update of the QuantMonitor Live Portfolio. This is a real-money portfolio where we publish results transparently and, just as importantly, we

Required membership: Free (Activate the plan here) Type: Breakout TimeFrame: H1 Profit factor 1.47 Instrument: Forex Supported platforms: MetaTrader 4, MetaTrader 5, StrategyQuant Strategy description This Brent H1
Required membership: Free (Activate the plan here) Type: Breakout TimeFrame: H1 Profit factor 1.38 Instrument: Forex Supported platforms: MetaTrader 4, MetaTrader 5, StrategyQuant Strategy description This is the first

Introduction: Markets as Rhythmic Systems Financial markets are often described as unpredictable, chaotic, and driven by random events. Yet a deeper historical examination reveals a

At QuantMonitor, we combine more than thirty years of collective experience in algorithmic trading, systematic research, and portfolio engineering. Over the past months, I have

The QuantMonitor Live Portfolio continues to focus on controlled, systematic growth rather than aggressive equity acceleration. The primary objective remains long-term robustness: strict risk management, diversification across

Throughout this year’s live trading and the continuous monitoring of a wide spectrum of strategies, one pattern has become increasingly evident: Scalping strategies on the

After exploring the full workflow of building strategies, working with templates, and deploying/monitoring algorithms inside the QuantMonitor ecosystem, it’s time to look at the part

A complete workflow for building, testing, and deploying algorithmic trading strategies like a professional trader. The QuantMonitor Premium Dashboard is not just a collection of

Trend + Volatility Filters With Keltner Channel and ATR At QuantMonitor, we combine more than 30 years of collective experience in algorithmic trading, systematic research and portfolio

We have completed the eighth month of our live algorithmic portfolio, and the results continue to confirm the strength, consistency, and long-term sustainability of our
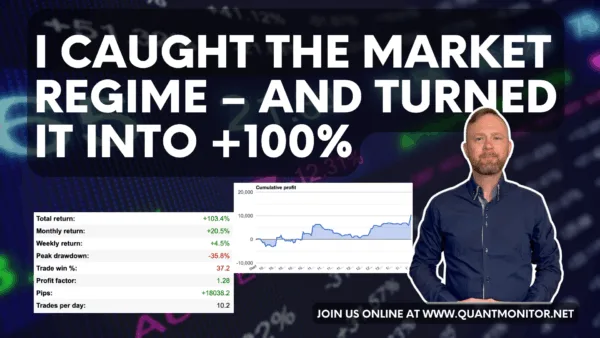
A market-regime filter is a rule that only lets a strategy trade when the market is in a favourable state. QuantMonitor’s version switches a strategy